

Principal® analysis by Appwee
I approached Principal® as a practical finance companion rather than an app I would open for entertainment. Its purpose is straightforward: help me keep an eye on financial goals while I am away from a desktop computer. That sounds modest, but it matters when financial tasks are usually postponed because they feel too formal, too slow, or too disconnected from daily life.
After spending time with it, my view is that its real value depends less on novelty and more on whether it becomes part of a repeatable routine. The app is free, aimed at Everyone, and developed by Principal Financial Group, Inc. That combination makes it easy to try, but the more important question is whether it continues to deserve a place on your phone once the first-week curiosity has gone.
What the first week feels like
The first appeal is convenience. A finance app can remove the need to wait until I am at a computer to check progress, review an account, or reconnect with a longer-term objective. Principal® is designed around that on-the-go use, so I found it most useful during small gaps in the day: before a scheduled payment, after receiving income, or when I wanted to confirm that my financial plans were still moving in the right direction.
I would not describe the experience as a replacement for every financial tool I use. Instead, it works best as a focused window into the Principal ecosystem. That distinction is important. Someone looking for a complete household budgeting system, detailed spending categorization, or a broad view of accounts from many unrelated institutions may expect more than this app is meant to provide.
The app’s strongest early impression is that it gives financial goals a more immediate presence. Long-term planning can feel abstract when it lives in paperwork or an occasional desktop session. Having access through a phone makes it easier to check in before a decision rather than after one. That does not automatically improve financial behavior, but it lowers the friction between intention and action.
Principal® has been available since March 1, 2019, and its current version is 4.0.146. Those details suggest a product with an established history rather than a brand-new experiment. In practical terms, I prefer that maturity for a finance app: I want something that feels maintained and familiar enough to support a recurring habit, not an attractive prototype that may disappear after a few months.
The reception is also encouraging. The app holds a 4.7 average from around 44 thousand ratings, with more than two thousand written reviews, and it has passed one million installs. I treat those figures as a sign of broad usefulness rather than a guarantee that every financial workflow will suit me. Finance apps are especially personal; a feature that feels essential to one person may be irrelevant to another.
A realistic everyday workflow
Imagine I am preparing for a busy week and want to make sure a financial goal has not been neglected. Instead of opening a laptop and turning the check into a major task, I can use the mobile app during a short break to review the information available through my Principal relationship. If something needs attention, I can deal with it while the context is fresh. If nothing needs changing, the quick check still reassures me that the plan has not slipped out of sight.
That small interaction is where the app makes the most sense. It is not about staring at financial screens every day. It is about giving important decisions a convenient checkpoint. I found that this approach works better when I decide in advance what I am checking. A vague habit of opening a finance app can become unproductive scrolling; a specific question, such as whether a goal is on track or whether an account needs review, keeps the visit useful.
One practical tip is to separate monitoring from decision-making. I would use the phone for a quick status review, then take more time before making a significant change. Mobile access is excellent for awareness, but a smaller screen and a rushed moment are not always ideal for weighing complicated choices. Principal® earns trust when it helps me notice what deserves attention, not when it encourages impulsive adjustments.
Where it fits among finance alternatives
Compared with a traditional website, the app is more convenient for brief check-ins and less dependent on being at a desk. Compared with a general budgeting app, it is more closely tied to Principal’s financial services and goals rather than serving as a universal dashboard for every part of my financial life. Compared with spreadsheets, it is less flexible but far easier to consult when I am away from a computer.
That trade-off determines who should install it. If your main relationship is with Principal and you want mobile access to that financial activity, the app has a clear role. If you want to combine numerous banks, cards, loans, and household expenses in one neutral workspace, a dedicated aggregation or budgeting tool may be a better primary choice. I would not force Principal® to perform that broader job.
The same applies to people who enjoy building detailed financial models. A spreadsheet can expose every assumption and let me design unusual calculations. A mobile finance app is better for keeping a plan visible and manageable. I see Principal® as the companion to a financial plan, not necessarily the place where I would construct the entire plan from scratch.
Why it can remain useful after the novelty fades
Month-to-month value comes from repetition
The long-term case for Principal® is not a dramatic transformation after one session. Its value builds through repeated, low-effort awareness. Financial goals often fail quietly: a review is delayed, a question is forgotten, or a person stops looking because the process feels inconvenient. A mobile checkpoint can interrupt that pattern.
I think the best recurring use is a scheduled review that matches the rhythm of real finances. For one person, that may be around income dates; for another, it may be a monthly planning session. The app does not need to become a daily ritual to be valuable. In fact, daily checking may create unnecessary worry when the underlying goals are long term. A calm, consistent review is more sustainable than constant monitoring.
Another useful habit is to pair the app with a written question. Before opening it, I would note what I want to understand. Am I checking whether a contribution occurred? Am I reviewing progress? Am I looking for something that needs follow-up? This simple step turns an open-ended visit into a maintenance task with a clear finish line.
That matters because finance apps can create the illusion of progress. Opening an account screen feels productive, but it is not the same as improving a plan. Principal® is most valuable when the information leads to a sensible next step, even if that step is simply recording a result and moving on. I would judge the app by whether it helps me maintain awareness, not by how often I open it.
Maintenance without turning finance into a chore
The maintenance burden is fairly manageable when expectations are realistic. I would keep the app available for quick reviews, but I would not rely on it as my only record of financial decisions. Important choices deserve notes, dates, and context outside a single mobile session. That is not a criticism unique to this app; it is a sensible safeguard for any finance tool.
There is also a difference between maintaining the app and maintaining the financial plan. Updating the application is a technical task, while reviewing goals is a personal one. The current version indicates ongoing development, but no update can decide whether a target still fits my life. I still need to revisit priorities when income, expenses, or responsibilities change.
My preferred routine would be deliberately small. I would keep notifications, if I choose to use them, limited to information that helps me act. I would review the app at a predictable interval, write down anything that needs follow-up, and avoid repeatedly reopening it just to seek reassurance. This keeps the tool from becoming another source of digital noise.
A second tip is to use the app as a trigger for questions, not as a substitute for understanding. If a figure or status seems unfamiliar, I would pause and investigate rather than guessing. Finance interfaces can make information look simple while the underlying decision is not. The app is helpful when it makes me more attentive; it is less helpful when convenience encourages me to skim.
What may cause fatigue over time
The first source of fatigue is scope. If I want one place for every account and every spending category, a Principal-focused app may feel narrow. That is not necessarily a weakness in its intended role, but it becomes a limitation when my financial life is spread across several providers. Switching between apps can undermine the very convenience I wanted.
The second source is emotional. Long-term progress can be slow, and checking repeatedly may produce little visible change. A user who expects constant movement may become disappointed even when the plan is working normally. I would use the app to support periodic decisions, not to demand a new result every time I open it.
The third source is the risk of confusing access with advice. The app can make financial information easier to reach, but that does not mean every situation can be resolved through a quick screen review. Complex retirement questions, tax concerns, or major changes in circumstances may require more careful research and professional guidance. I would not treat mobile convenience as a replacement for judgment.
There is also a habit-related fatigue that affects many finance products: the app can become part of a crowded phone routine. If I install it without deciding when and why I will use it, it may be forgotten. The way around that is not to force daily engagement. It is to give the app one clear job, such as a monthly progress check, and let that job justify its place.
Who should use it, and who should skip it
I would recommend Principal® to someone who already uses Principal Financial Group, Inc. and wants a convenient mobile way to stay connected with financial goals. It is especially suitable for people who prefer short, regular reviews over occasional desktop sessions. The free price also removes an obvious barrier to trying it, although the more meaningful question is whether its connection to your financial relationship makes it relevant.
I would be more cautious if you are searching for an independent budgeting command center. Someone who needs extensive spending analysis, broad account aggregation, or highly customized planning may find a specialized alternative more appropriate. In that case, Principal® could still serve as a provider-specific companion, but I would not expect it to replace the broader tool.
I would also skip it as a primary choice if you dislike mobile finance management altogether. Installing an app does not solve a planning problem when the real obstacle is uncertainty about goals or a lack of time to review them. A simple written plan or a scheduled conversation may be more useful until those basics are in place.
Privacy-minded habits and practical caution
Because this is a finance app, I would treat phone security as part of the experience. I would keep the device protected, avoid reviewing sensitive information on an unsecured shared device, and make sure I understand which account I am viewing before taking action. These are ordinary precautions, but they matter more here than they would in a casual utility app.
I would also avoid making a major decision while distracted. The app’s on-the-go design is useful, yet convenience can tempt me to rush. My rule would be simple: use the phone for awareness and straightforward maintenance, then move to a calmer setting when the decision has lasting consequences.
My long-term verdict
After the novelty fades, Principal® earns its space when it supports a modest but dependable habit. I do not see it as a universal financial command center, and I would not recommend it to someone whose main need is detailed budgeting across unrelated providers. Its strength is more focused: keeping Principal-related financial goals close enough to review before they disappear into the background.
The app’s free availability, Everyone age rating, established release history, and strong reception make it easy to consider. More importantly, its usefulness does not depend on opening it constantly. A well-timed monthly review can be more valuable than frequent checking without a purpose. That is the kind of recurring value I look for in a finance app.
My recommendation is therefore conditional but positive. If Principal is already part of your financial life, I would install it and build a light routine around specific questions and follow-up actions. If you need a complete, provider-neutral budgeting system, I would choose a different primary tool and use this one only for its Principal connection. In the right role, it is not flashy, but it is practical—and practicality is what gives a finance app a lasting place on my phone.
Gallery
Principal® Pros and Cons
- Simple interface makes daily habit tracking quick to manage.
- Flexible reminders help users stay consistent with routines.
- Progress views make long-term behavior changes easier to evaluate.
- Supports multiple habits for personal
- health
- and productivity goals.
- Useful for users who prefer structured
- goal-focused self-improvement.
- Some advanced features may require a paid subscription.
- Habit setup can feel limited for highly complex routines.
- Frequent reminders may become distracting for some users.
- Progress insights may not satisfy users seeking detailed analytics.
- Requires regular manual updates to keep tracking accurate.
Principal® Frequently Asked Questions
What is Principal® and what can I do with it?
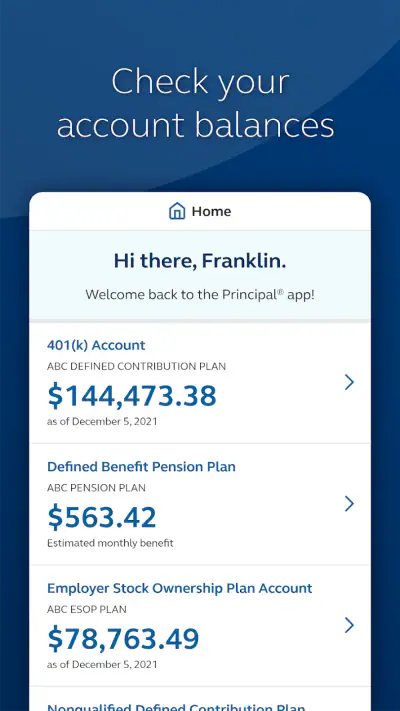
Principal® is a financial and insurance services app designed to help eligible users manage products connected with Principal Financial Group. Depending on your account and region, you may be able to review retirement or investment balances, check transactions, view statements, monitor performance, manage contributions, access insurance information, and contact support. Available tools can differ according to the products registered to your profile.
Is Principal® free to download and use?
The Principal® app is generally available to download without an upfront charge, but using it may involve the normal fees, expenses, or plan charges associated with your retirement, investment, or insurance products. Your mobile carrier may also apply data charges. Before making decisions, review the fee information provided for your specific account, since app access does not remove product-related costs.
How do I sign in to Principal® and is biometric login supported?
You normally sign in with the credentials associated with your Principal account. After completing the initial setup, the app may allow supported devices to use fingerprint or facial recognition for faster access. Keep your operating system and app updated, and never share passwords or verification codes. If you cannot sign in, use the official recovery options or contact Principal support.
Can I manage my retirement or investment account through Principal®?
For supported accounts, Principal® can provide convenient access to balances, contributions, investment allocations, performance information, statements, and certain account-management features. What you can change depends on your employer plan, account type, permissions, and location. The app should be treated as a management and information tool, not as personalized financial advice; consider your circumstances before changing investments or contributions.
Is Principal® safe for viewing personal and financial information?
Principal® is intended to use security measures such as account authentication, encrypted connections, device protections, and additional verification features where available. However, no online service is completely risk-free. Download the app only from an official store, avoid signing in on public or rooted devices, enable screen locking and biometric security, and contact Principal promptly if you notice suspicious activity.














